Most New Year’s financial resolutions collapse before January ends. People boldly declare they will save five hundred dollars every single month. By mid-February, an unexpected car repair hits, enthusiasm vanishes, and old spending habits rush right back in.
The problem is not lack of willpower. The problem is starting with an intimidating goal that shocks your daily lifestyle. True financial endurance is built the same way marathon runners train: starting with light, effortless steps and progressively building strength.
This is why the 52-Week Money Saving Challenge has become a viral phenomenon. By saving just a single dollar during week one, you gently rewire your spending psychology while accumulating exactly \$1,378 in cash by the end of the year.
How the Traditional 52-Week Challenge Operates
The mathematical mechanics of the classic 52-week challenge are brilliantly simple. You match your weekly savings deposit to the number of the week in the year.
- Week 1: You deposit \$1.00
- Week 2: You deposit \$2.00
- Week 3: You deposit \$3.00
- Week 26 (Halfway): You deposit \$26.00 (Total saved so far: \$351.00)
- Week 50: You deposit \$50.00
- Week 52: You deposit \$52.00
When you complete the final deposit in week 52, you have accumulated exactly \$1,378.00. Because the deposits start so small, you barely notice the money leaving your pocket during the first three months.
The Flaw in the Traditional Method (And the Smart Fix)
While the classic format is popular, it contains one critical design flaw that causes many participants to quit in December.
In the traditional format, the highest deposit weeks arrive in November and December. During week 49 through 52, you must deposit over two hundred dollars in cash—at the exact time holiday gifts, travel expenses, and festive dinners strain your budget to the limit.
To avoid holiday burnout, consider two proven variations:
- The Reverse 52-Week Challenge: Start with week 52 in January when enthusiasm is high, depositing \$52.00. Each week, reduce your deposit by one dollar (\$51, \$50, \$49). By December, your weekly deposits drop to just \$4, \$3, \$2, and \$1 when holiday spending peaks.
- The Bingo / Flexible Format: Print out a grid with numbers 1 through 52. On weeks when you receive extra overtime or a cash bonus, cross off the high numbers (\$50, \$52). On tight weeks, cross off \$3 or \$5. You get the same \$1,378 with zero seasonal pressure.
Where to Stash Your Weekly Challenge Money
Leaving your challenge cash sitting in your everyday checking account is an open invitation for accidental spending.
You have two effective choices depending on your personality:
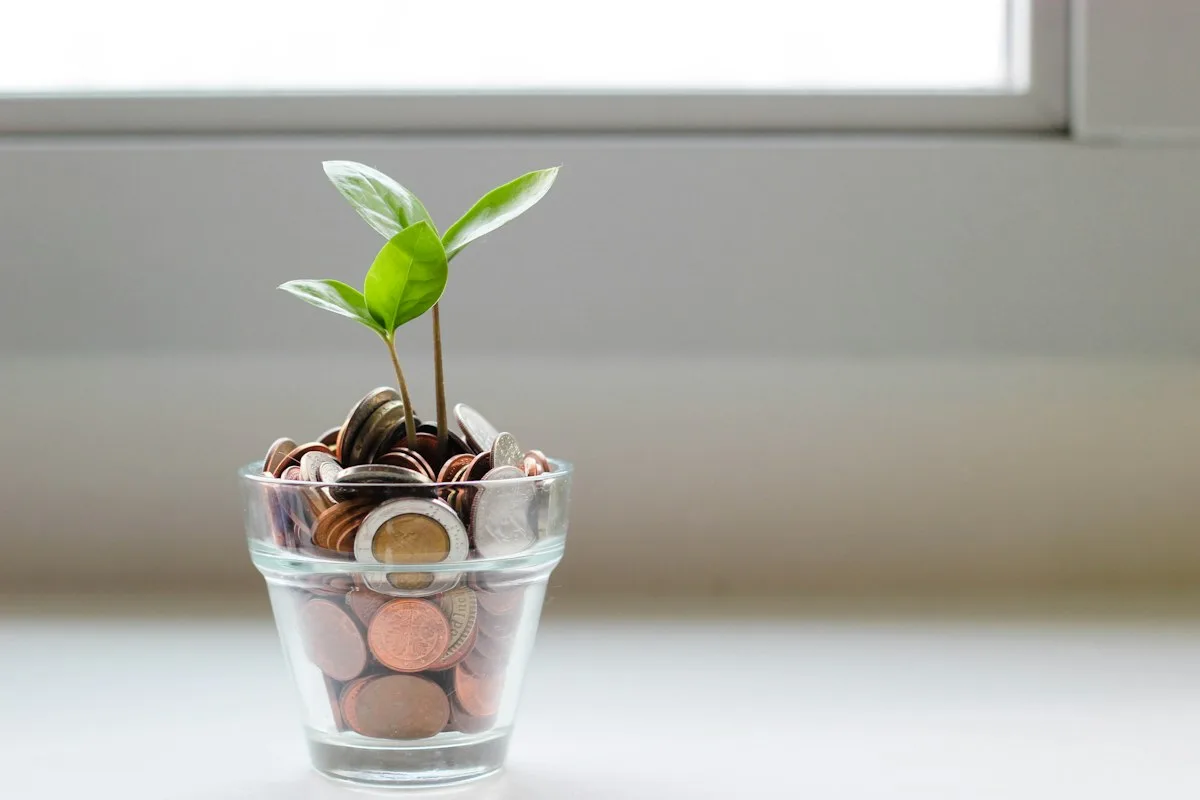
- Physical Cash Mason Jar: If you are a tactile, visual person, keep a designated glass jar on a high bookshelf. Dropping physical bills into the jar and watching the stack thicken creates immense psychological satisfaction.
- High-Yield Savings Account (HYSA): If you prefer digital banking, open a dedicated sub-savings account named “52-Week Challenge” at an online bank offering four to five percent APY. You earn an extra forty dollars in free interest while keeping your savings safe from debit card swipes.
Building Weekly Triggers: The Sunday Ritual
A challenge that relies on memory will fail. You need a dedicated weekly trigger to make your deposit automatic.
Pair your savings deposit with an existing Sunday morning habit, like enjoying your first cup of coffee. Pull out your printed challenge tracker, move the money into your jar or savings account, and highlight the week’s box with a bright colored marker. Taking two minutes every Sunday morning cements this behavior into a permanent financial reflex.
What to Do with Your \$1,378 Cash Win
When you finish week 52, resist the urge to blow your accumulated funds on an impulse shopping spree. Use this cash strategically to elevate your financial stability:
- Starter Emergency Fund: If you have zero savings, leave this \$1,378 untouched in an emergency account. You are now permanently protected from minor financial emergencies.
- High-Interest Debt Payoff: Wipe out an entire store credit card balance or medical bill in one decisive payment.
- Sinking Fund for Next Year’s Holidays: Leave this money earmarked for upcoming holiday gifts, allowing you to celebrate December completely debt-free.
What Usually Happens in Real Life vs. What People Expect
People expect that saving money will feel restrictive and stressful.
In practice, the 52-week challenge feels like playing a game against yourself. Crossing off boxes on a printable sheet gives you small weekly dopamine hits. Instead of dreading finances, you look forward to checking off another box. By week twenty, you begin examining your daily spending to see what unnecessary expense you can trim to check off next week’s box early.
What Most People Overlook
People focus entirely on the final \$1,378 dollar amount. What they overlook is the neural habit formed across 52 consecutive weeks.
Saving money once or twice a year during tax refund season does not change your financial life. Saving money fifty-two weeks in a row permanently rewires how you handle income. You transition from a consumer who spends every penny into an accumulator who naturally saves first.
The Most Common Mistake Beginners Make
The most common mistake is quitting entirely after missing a single week. Life happens—you might catch the flu or face an urgent bill and miss week sixteen.
Missing one week is not failure; quitting is. If you miss a week, do not try to double your deposit next week and overwhelm yourself. Simply pick up right where you left off. Taking fifty-four weeks to reach \$1,378 is infinitely better than abandoning your goals in March.
